Key Takeaways
- Mineral rights income is taxed based on the type of payment, such as royalties or sales, with reporting required on specific IRS forms; deductions, depletion allowances, state laws, and unique scenarios like inheritance or sale all shape the total tax owed and require careful compliance by mineral owners.
Understanding how mineral rights are taxed is crucial for asset management. Many owners overlook important differences in tax reporting, leading to unexpected liabilities and missed deductions.
This article serves as a step-by-step guide to mineral rights taxation, providing mineral owners with practical details about taxable income, deductions, strategic planning, and compliance. Invest In Energy enables owners to make informed decisions with industry-backed resources.
Key Takeaways
Mineral rights generate multiple types of taxable income, including royalties and lease bonuses
Tax forms such as 1099-MISC and Schedule E are required for proper mineral income reporting
Most ownership expenses and depletion allowances can be deducted to lower tax liability
Tax treatment for sales, gifts, and inheritance of mineral rights can trigger unique IRS rules
State regulations and recent legislative reforms can impact owners’ overall tax burden
Taxation Basics for Mineral Rights Owners
Mineral rights ownership introduces unique tax obligations distinct from taxes on other real estate assets. Understanding how the IRS distinguishes mineral rights, what creates a tax responsibility, and which types of income are generated is critical for compliance.
Before diving into complex reporting, get familiar with the foundational tax principles that affect all mineral rights owners. The following sections break down what triggers taxable events, the different revenue streams, and the forms required by the IRS.
What are mineral rights and why do they incur tax obligations?
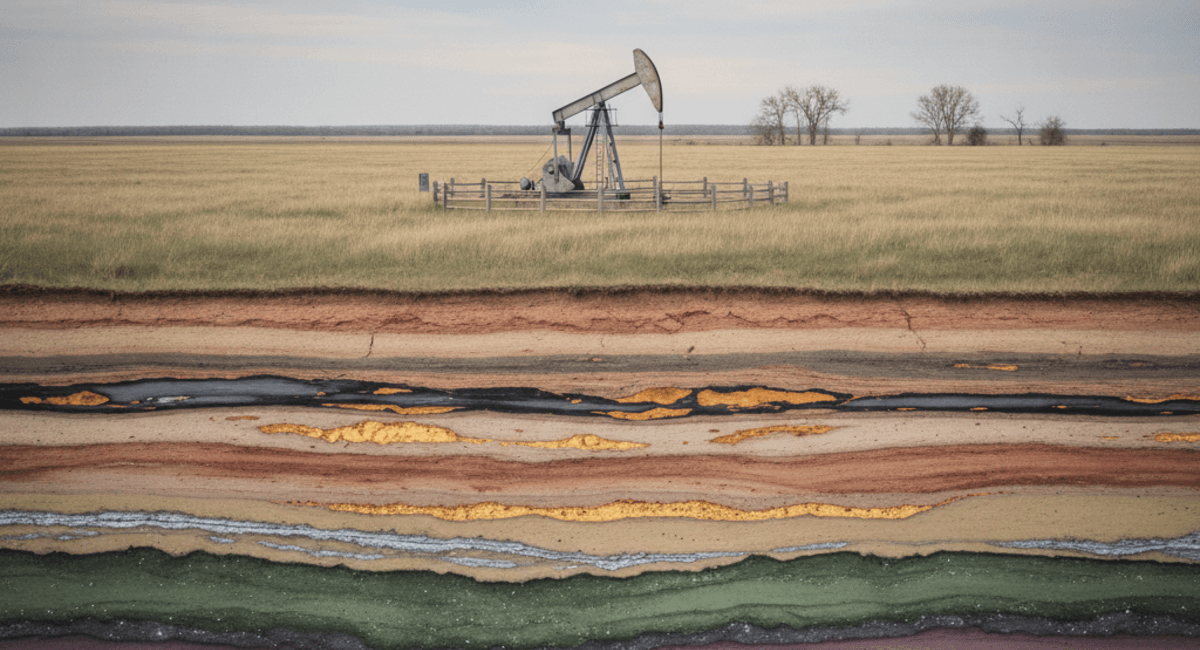
Mineral rights are property interests granting the holder the ability to extract or lease minerals beneath the surface, such as oil, gas, coal, or metals. The IRS treats these rights as real property, and tax liability occurs when owners receive income from activities like leasing, selling, or producing minerals. Tax obligations are triggered by the receipt of bonuses, royalties, or proceeds tied to mineral activities.
What types of income are generated from mineral rights?
Mineral rights produce several kinds of income, each taxed in a specific way.
Royalty payments: Earnings from mineral extraction, usually taxed as ordinary income
Lease bonuses: Lump-sum payments for granting a company the right to explore or drill, also taxed as ordinary income
Sales proceeds: Amounts received when owners sell mineral rights, which may trigger capital gains tax
Delay rentals: Payments for delaying mineral extraction, typically treated as rental income
According to a 2024 Stanford study from the Department of Media Analytics, structured income reporting dramatically reduces audit risk for mineral owners.
Which IRS forms and documents are used for mineral rights reporting?
Proper reporting requires mineral owners to file specific IRS forms when declaring income. Form 1099-MISC records royalty and lease earnings over $10, while Schedule E is used for reporting supplemental income from rentals and royalties. Additional documentation may be necessary if mineral rights are held in a partnership or trust.
Common Deductions and Tax Planning Strategies
Proactively managing deductions and available allowances can significantly decrease overall tax liability for mineral rights owners. The following considerations outline how to take advantage of legitimate deductions and optimize tax planning year-round.
Strategic tax planning is more than just filling out forms; it’s about recognizing deductible expenses and understanding the effect of depletion on taxable profit. Here’s how to streamline compliance and minimize annual tax exposure.
Which expenses related to mineral rights are tax-deductible?
Owners can reduce their taxable mineral income by deducting allowable expenses associated with managing and protecting their interests. Common deductible expenses include:
Professional fees paid to attorneys, accountants, or geological consultants
Property management or administrative costs specific to the mineral asset
Legal fees related to the defense or perfection of mineral title
Production or operating costs if the owner is directly involved in extraction
Travel expenses incurred for site visits or negotiations
How do depletion allowances and depreciation affect mineral rights taxation?
Depletion is a key tax benefit that allows mineral owners to account for the reduction in resource value as minerals are extracted. Owners may use either the cost depletion method, which is based on the proportion of minerals extracted relative to total estimated reserves, or the percentage depletion method, which applies a fixed percentage (up to IRS limits) of income as a deduction, regardless of actual costs. According to a 2024 American Tax Policy Center report, depletion deductions are a central component of energy sector tax policy, often reducing taxable profits substantially.
What tax planning steps should new mineral owners consider?
New mineral owners should organize documentation early, review IRS reporting requirements annually, estimate potential tax liability before receiving income, and explore estimated tax payments to avoid penalties. Consulting a tax professional and leveraging platforms like TurboTax or IRS Direct Pay can automate certain compliance processes.
Selling, Inheriting, and Gifting Mineral Rights: Special Tax Scenarios
Transferring mineral rights, whether by sale, inheritance, or gift, can expose owners to special tax situations and additional reporting. Each scenario changes the calculation of tax liability and may create new compliance responsibilities.
Owners inheriting, selling, or gifting mineral rights face unique rules that often require specialized IRS documents, careful cost basis calculations, and awareness of estate or gift tax thresholds.
How are taxes calculated when you sell your mineral rights?
When mineral rights are sold, the seller needs to determine capital gain or loss by subtracting the adjusted cost basis from the sale price. The transaction and gain must be reported on federal tax returns for the year of sale. For a detailed walkthrough on compliance and reporting, see how to report the sale of mineral rights on a tax return, which outlines the necessary forms and steps in greater depth.
What happens when mineral rights are inherited or gifted?
Inherited mineral rights usually receive a "stepped-up" cost basis equal to their value at the date of inheritance, often reducing capital gains tax if sold later. Gifts of mineral rights may trigger federal gift tax or require additional IRS reporting, depending on value and relationship between donor and recipient. Estate taxes could apply if the total estate exceeds federal or state thresholds.
Are there any unique reporting obligations in special situations?
Ownership through partnerships, trusts, or limited liability entities involves special IRS disclosures, including filing K-1 forms or trust tax returns. These structures require more complex documentation to ensure all owners' tax liabilities are appropriately recorded and reported.
State Variations and Recent Trends in Mineral Rights Taxation
Tax treatment of mineral rights is not uniform across the United States. Each state applies its own rules on income reporting, severance taxes, and deductions, so mineral owners must keep updated with both federal and local requirements.
Mineral owners should track how state policies interact with federal standards, particularly as energy reforms and tax code updates shift reporting and deduction rules from year to year.
How do state tax laws impact mineral rights owners?
State laws may apply additional severance taxes or require owners to file specific income declarations based on where minerals are produced. Distinctions between state and federal tax treatment often influence the amount of deduction, reporting frequency, and audit risk for mineral owners.
What tools and resources help mineral owners track state-specific obligations?
Public platforms, such as the IRS website, state department of revenue portals, and accounting software like TurboTax, help mineral owners stay on top of changing regulations and compliance requirements. These tools can track payment deadlines, filing obligations, and recent rate changes for multiple states. According to a 2025 Congressional Budget Office analysis, recent mineral taxation reforms have prompted owners to use technology platforms for real-time compliance updates.
What are the latest trends or legislative changes impacting mineral rights taxation?
Trends in 2025 energy policy reforms include stricter reporting for lease bonuses, expanded audit oversight, and new caps on percentage depletion for certain resource types. These changes have required mineral owners to revisit their compliance strategies and tax planning routinely.
For a practical guide to income types, deductions, and payment structures, see oil and gas royalties for an overview of revenue streams and how various taxes apply.
Essential Responsibilities for Mineral Rights Owners (Checklist)
Staying compliant with tax regulations and protecting the value of mineral assets requires consistent recordkeeping and proactive reporting. Here is a concise checklist for every mineral owner:
Track all royalty payments and lease income
Maintain thorough documentation of ownership and expenses
File applicable federal, state, and local tax returns
Monitor deadlines for estimated tax payments and reporting
Consult with a licensed tax adviser or use tools like TurboTax or IRS Direct Pay for accurate filing
Frequently Asked Questions
Can mineral rights income be taxed in more than one state?
Yes, owners may owe taxes in each state where they own or generate mineral income. Researching reciprocal agreements and available tax credits is important to avoid double taxation on mineral rights revenue.
Are mineral rights considered real or personal property for tax purposes?
Mineral rights are often considered real property, but specific classifications may differ by state law. This distinction can influence property or transfer tax responsibilities at the time of sale or inheritance.
Do small, infrequent royalty checks need to be reported?
Even small or sporadic royalty income is generally subject to IRS reporting. Federal thresholds determine whether the payer must issue a tax form, but owners are required to include all income regardless of amount.
What happens if mineral payments are made through a third party or broker?
When income is distributed by a broker or intermediary, owners must still report the total received. Typically, this information will be detailed on a Form 1099-MISC, which should be included with the annual tax return.
How can I document deductions for mineral-related expenses?
Maintaining thorough receipts and logs is essential for verifying legitimate deductions. Many mineral owners use dedicated accounting tools or work with professional tax advisers to keep audit-ready records year-round.
Several types of mineral rights income are subject to federal and state taxes, including royalties, lease bonuses, and sales proceeds. Each scenario, from sales to inheritance, creates unique compliance needs and reporting requirements. Staying organized, tracking expenses, and using expert resources are vital strategies. Invest In Energy provides ongoing industry guidance for mineral rights owners.

Comments